Alberto Heimler argues that antitrust authorities should focus on whether market power allows one party to exploit relationship-specific sunk investments made by another and how that undermines potential innovation, investments, and competition.
Competition authorities and antitrust scholars are reconsidering some of the central questions of antitrust policy: how to assess practices by dominant firms, including digital platforms; how to address labor-market restraints; how to control mergers without jeopardizing growth and innovation; and, more generally, what competition law is intended to achieve. The European Commission’s revision of its Article 102 competition guidelines and its recent consultation on revised merger guidelines have made steps in advancing enforcement standards. But these reforms will have limited effect unless the underlying analytical framework is also reconsidered. Updating individual rules may improve enforcement at the margins, but leaves unresolved the more basic question of what unifies antitrust policy.
Regulators around the world have struggled to establish uniform ways to evaluate the competitive merits and harms of mergers and business practices. In the United States, criticism of the consumer welfare standard, which directs attention to how a business practice impacts prices and output, has not yet produced a convincing alternative.Broader standards that make references to public welfare considerations— like labor, inequality, or political power—have not clarified how to handle specific cases. Europe has largely avoided that debate but has developed an increasingly varied set of objectives: the protection of competition, market integration, fairness, workers’ well-being, and innovation. These are all legitimate concerns, but they do not by themselves provide a common analytical principle. The result, in both jurisdictions, is continuing uncertainty about the purpose and limits of antitrust enforcement.
One of the core criticisms of the consumer welfare standard is that a focus on short-term changes in prices may prevent regulators and courts from evaluating important long-term outcomes. A focus on market power can represent the way forward. However, the conventional concept of market power, which is determined when prices are above their competitive level, is too broad to provide, by itself, an operational basis for antitrust enforcement and indeed the ability of a firm to charge supra competitive prices may result from successful investment and innovation and may itself be necessary to preserve the incentives to invest.
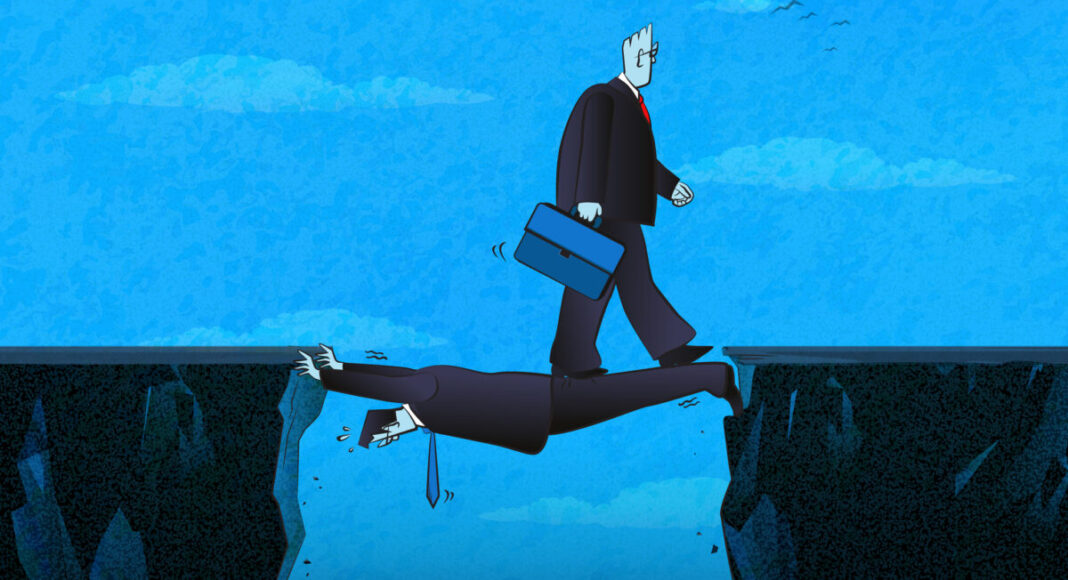
A more sophisticated question asks whether the exercise of market power or simply the threat of its exercise would change the confidence that firms, workers, and consumers have to undertake relationship-specific investments whose returns may later be appropriated by a trading partner. Workers acquire skills and institutional knowledge specific to a firm, suppliers invest in customized production lines and in connecting to infrastructures, intellectual property users invest in complementary activities, developers write tailored software, and consumers invest time in learning products and ecosystems. The antitrust problem then becomes preventing that, once these investments are sunk, trading partners with market power may take advantage of the investor’s reduced ability to switch in order to appropriate part of the expected return from these investments, negatively affecting the incentives to invest. Economists describe this ex post appropriation of the returns from sunk relationship-specific investment as the hold-up problem.
Seen from this perspective, a number of difficult antitrust questions become more closely related. Labor-market restraints, platform disputes, exploitative abuses, self-preferencing, refusals to deal, mergers, and cartels may all involve, in different ways, the appropriation of relationship-specific investments by trading parties.
Competition is normally the main safeguard against this market power. If one trading partner seeks to appropriate the value of an investment, alternative suppliers or customers limit its ability to do so. Where those alternatives disappear, and contracts cannot adequately address the risk, the ability to hold up the investing party may provide a possible justification for antitrust intervention.
Market power is inherently relational: a firm may have substantial market power over trading partners that have made specific sunk investments while having little or no power over others that retain effective alternatives. Conversely, market power in the conventional sense—such as the ability to charge prices above the competitive level—would not in itself call for intervention where it does not involve the exploitation of relationship-specific sunk investment. This is broadly consistent with antitrust enforcement practice, but provides it with a clearer, more cohesive economic foundation.
This definition also helps explain why market power need not manifest itself in higher prices. It may appear in lower wages, less favorable contractual terms, reduced access, changes in platform conditions, or other forms of appropriation. What matters for antitrust is whether the ability to exploit sunk relationship-specific investment is sufficiently significant to weaken the incentive to undertake valuable investments in the first place.
The advantage of a sunk investment-based framework is that it can be applied consistently across output markets, input markets, labor markets, and digital ecosystems.
Telecommunications, pharmaceuticals, energy, and many other sectors depend on the expectation that investments made today will generate returns over a long period. If firms or consumers fear that those returns may later be appropriated by trading partners, investment is likely to decline, with eventual effects on innovation, productivity, and living standards.
This perspective also affects the analysis of familiar legal questions.
Consider refusals to deal. Current analysis asks mainly whether denying access to a competitor is likely to reduce competition, increase prices, or restrict output. Those questions remain important, but they should be complemented by an assessment of investment incentives. If a dominant firm uses its position to appropriate the returns from sunk investments made by customers, suppliers, or rivals, intervention may be justified even where short-term price effects are difficult to establish. At the same time, routinely requiring firms to share assets or technology may itself discourage investment if successful investment leads automatically to access on terms the investor cannot control. The objective should therefore be neither to maximize access nor to protect competitors as such, but to preserve the investment incentives on which competition depends over time. The implications of this argument extend well beyond refusals to deal.
Defenders of the consumer welfare standard often allege that alternatives rely on flimsier economic analysis. On the contrary, a framework based on relationship-specific investments calls for a fuller use of economic analysis. Investment incentives, bargaining relationships, transaction costs, and contractual structures have long occupied a central place in economic theory, but competition law has often treated them as secondary considerations. Giving them a more explicit role would not weaken traditional antitrust enforcement. Cartels remain harmful because collective market power may allow firms jointly to appropriate the returns from relationship-specific investments made by customers and suppliers. Mergers may also require intervention where, by reducing the choices available, they materially increase the ability to appropriate the returns from sunk investments made by customers, suppliers, or workers. The point is to give antitrust enforcement a clearer and more coherent economic foundation, while making it a strategic policy tool fit for modern economies.
Across jurisdictions, placing relationship-specific sunk investments at the center of the analysis would help bring greater coherence to the treatment of labor-market restraints, digital-platform practices, exploitative abuses, refusals to deal, cartels, and mergers. It would also connect antitrust more directly with the wider concern that Europe and other economies need to maintain strong incentives to invest, innovate, and raise productivity.
Author’s Disclosures: The author reports no conflicts of interest. You can read our disclosure policy here.
Articles represent the opinions of their writers, not necessarily those of the University of Chicago, the Booth School of Business, or its faculty.
Subscribe here for ProMarket’s weekly newsletter, Special Interest, to stay up to date on ProMarket’s coverage of the political economy and other content from the Stigler Center.