
Financial crises routinely trigger sweeping overhauls of financial regulation, but whose interests do these reforms serve? In new research, Orkun Saka, Yuemei Ji, and Clement Minaudier find that political leaders facing term limits are much more likely to respond to financial crises by introducing reforms that benefit banks over the public or long-term financial stability. This phenomenon occurs more frequently in countries where the revolving door between politics and finance is common.
Financial crises are an endemic feature of market economies. Their costs are severe—deep recessions, collapsing banking systems, and surging public debt—and they almost always prompt governments to rewrite the rules of the financial system. A long tradition in political economy sees this as a silver lining: crises weaken entrenched interest groups and open a window for necessary reforms. The advice often attributed to Winston Churchill, to never let a good crisis go to waste, captures this optimistic view.
But the same advice can be taken by those with narrower goals in mind. Whether the policies introduced after a crisis serve the general population or incumbent financial institutions remains an open question. In a new paper, we argue that the answer depends crucially on whether politicians can still be held to account at the ballot box.
Crises could strengthen or weaken accountability
Elections are a key mechanism to keep politicians acting in voters’ interests. Leaders who can seek another term must satisfy voters, while leaders facing a binding term limit cannot be punished at the next election. A large literature documents that this matters for policy, from taxation and spending by American governors to corruption among Brazilian mayors.
How economic crises interact with this mechanism is theoretically ambiguous. On the one hand, crises put financial regulation in the spotlight. Greater salience means more voter scrutiny, which should push politicians up for re-election towards policies that benefit the public. On the other hand, crises flood legislatures with activity, make information noisier, and mobilize special interests. Lobbying intensifies precisely when the stakes are highest, and the rewards that the financial industry can offer politicians who deliver favorable policies—including lucrative post-office jobs—rise accordingly. Such windows of opportunity are most valuable to politicians whose careers no longer depend on voters.
Comparing term-limited leaders with those eligible for re-election, before and after crises, allows us to see which of these forces dominates.
Four decades of financial policies
We combine two widely used databases on financial reforms—the original index by Enrica Detragiache, Abdul d Abiad, and Thierry Tressel and its extension to 2015 by Oliver Denk and Gabriel Gomes—to build a panel of seven dimensions of financial policy in 88 democracies from 1973 to 2015. The indices cover bank entry barriers, bank privatization, banking supervision, credit controls, interest rate controls, capital account restrictions, and securities market regulation, each scaled between zero (fully repressed) and one (fully liberalized). We date banking, currency, and sovereign debt crises using the International Monetary Fund database, which yields 173 crisis episodes in our sample.
Our key political variable, taken from the Database of Political Institutions, indicates whether a country’s executive leader is serving their last legally allowed term. Crucially, this varies over time within countries: in a two-term system, for example, the same president is eligible for re-election in the first term but term-limited in the second. This lets us compare leaders within the same country, while controlling for country-specific trends in liberalization and a rich set of fixed effects.
Lame ducks deliberalize after crises
Outside crisis periods, term-limited leaders and those eligible for re-election do not regulate finance differently. After a financial crisis, however, a sharp gap opens. Both types of leaders reverse financial liberalization—re-regulate, raise barriers to market entry, tighten capital and credit requirements—but term-limited leaders do so to a much greater degree. Relative to the average level of the liberalization index, a crisis reduces liberalization by about 3% under a leader facing re-election, but by more than 9% under a term-limited leader—a roughly threefold difference. To put this into perspective, the additional postcrisis effect of a term limit is about 30% larger than the baseline effect of having a right-wing government, which is traditionally more financially liberal, rather than a centrist government in power.
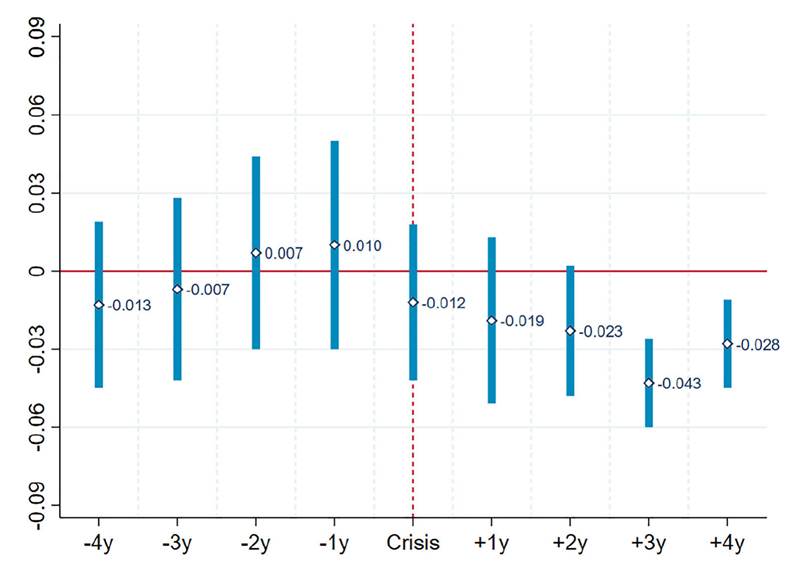
Figure 1 traces the timing of this effect. There is no differential behavior in the years before a crisis, which is reassuring. After a crisis hits, the gap between the two types of leaders grows gradually and peaks three to four years after the crisis starts.
Figure 1. Differential change in financial liberalization under term-limited leaders around financial crises
These results survive a battery of checks. They are unchanged when we control for how long the leader has been in office, the government’s vote share as a proxy for leaders’ mandate to enact change, ideology, government fragmentation, and whether the country has a presidential or parliamentary system. They also hold when we include rule out the possibility that the rise of extreme parties after crises drives the results. Dropping countries that never experienced a binding term limit during our sample makes the effect even stronger.
Incumbent banks benefit
Financial liberalization is a broad umbrella with different winners and losers, so we zoom in on three banking policies where the interests of incumbent banks and the general public diverge most clearly. Higher entry barriers protect incumbent banks from competition at the expense of consumers, who face higher prices and lower service quality. Increased bank supervision by the government is generally unwelcome to banks but valued by consumers. After crises, nationalization typically takes the form of bailouts through equity injections into troubled banks. This is support that the industry welcomes in the thick of the crisis but which voters view with considerable scepticism. All three policies represent reduced liberalization.
In the wake of crises, term-limited leaders are significantly more likely than their re-election-eligible counterparts to raise barriers to entry into the banking sector and to nationalize banks. They also tend to relax bank supervision, although that effect is not statistically significant. Notably, leaders facing re-election do not behave differently after crises than in normal times in these domains. The gap therefore stems from what term-limited leaders do after crises rather than from voters disciplining those seeking re-election. Greater salience of financial policy, in other words, does not appear to be the main force at work.
Following the revolving door
Why would term-limited leaders favor banks after crises? We present three pieces of evidence pointing to quid pro quo relationships between policymakers and the financial industry.
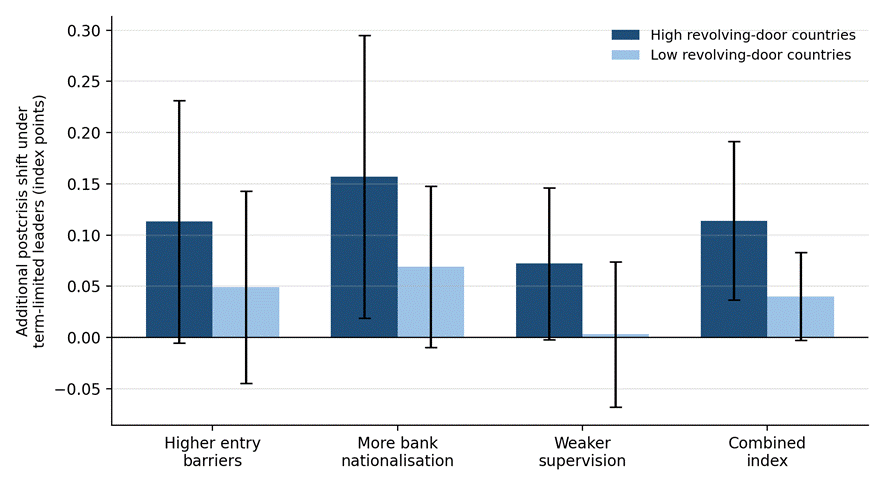
First, the relationship we observe is much stronger where revolving doors between politics and finance are common. Using the measure of Matías Braun and Claudio Raddatz, who rank countries by how often former high-ranking politicians sit on bank boards, we split our sample in two. As Figure 2 shows, the postcrisis shift towards bank-friendly policies under term-limited leaders is almost three times larger in high revolving-door countries than in low revolving-door countries.
Figure 2. Postcrisis shift towards bank-friendly policies under term-limited leaders, by revolving-door intensity
Second, we follow the careers of more than 500 finance ministers and central bank governors in 32 democracies, using data compiled by Elisa Wirsching. Officials who served under a term-limited leader in the aftermath of a crisis are about 30 percentage points more likely to take up a senior role—as president, board member, or adviser—in a private financial institution after leaving government. This is equivalent to more than three-quarters of the average probability of such a move in general. Serving under a term-limited leader or during a postcrisis period alone makes no difference: it is the combination that matters. Because our definition excludes state-owned financial institutions, the pattern is not a mechanical by-product of postcrisis nationalizations.
Third, a manual search of public records on the 106 term-limited leaders in our sample reveals that more than half had at least one link with their country’s financial industry—through paid roles after leaving office, cabinet members or officials with employment ties to banks, or corruption and family enrichment through the banking sector.
No gains for financial stability
One might argue that bank-friendly policies are exactly what a crisis calls for, and that the interests of banks and the public are aligned in the aftermath of a crisis. If so, banking sectors should perform better after crises when term-limited leaders are in charge. Using bank-level data from Bankscope covering 1999–2014, we find no evidence of this. Crises predictably weaken bank stability and performance across the board, but the policies pursued by term-limited leaders do not improve banks’ solvency, profitability, or loan performance. The policies favored by term-limited leaders do not deliver a more stable banking system.
Implications
Our findings suggest that crises are not uniformly good for reform. When electoral accountability is weak, crises can become opportunities to pass policies that benefit incumbent financial institutions at the expense of the public. The combination of a lame-duck leader, a crisis-induced legislative rush, and a well-trodden revolving door appears to be particularly potent.
This has implications for the design of institutions meant to keep policymakers accountable. Stricter cooling-off periods for senior officials moving into the financial sector, closer independent scrutiny of crisis-era financial legislation, and sunset clauses on emergency measures could all help narrow the windows of opportunity that crises open. More broadly, debates on term limits should recognize that their costs are not constant over time: they are likely to be highest precisely when the stakes for financial regulation are greatest. While our estimates capture robust conditional correlations rather than definitive causal effects, the consistency of the evidence across policies, careers, and bank outcomes points to a clear lesson: who is in charge when a crisis strikes, and what they expect to do next, matters for whose interests the new rules serve.
Author’s Disclosures: The authors report no conflicts of interest. You can read our disclosure policy here.
Articles represent the opinions of their writers, not necessarily those of the University of Chicago, the Booth School of Business, or its faculty.
Subscribe here for ProMarket’s weekly newsletter, Special Interest, to stay up to date on ProMarket’s coverage of the political economy and other content from the Stigler Center.